
Ind AS 112: Disclosure of Interests in Other Entities — A Complete Compliance Guide
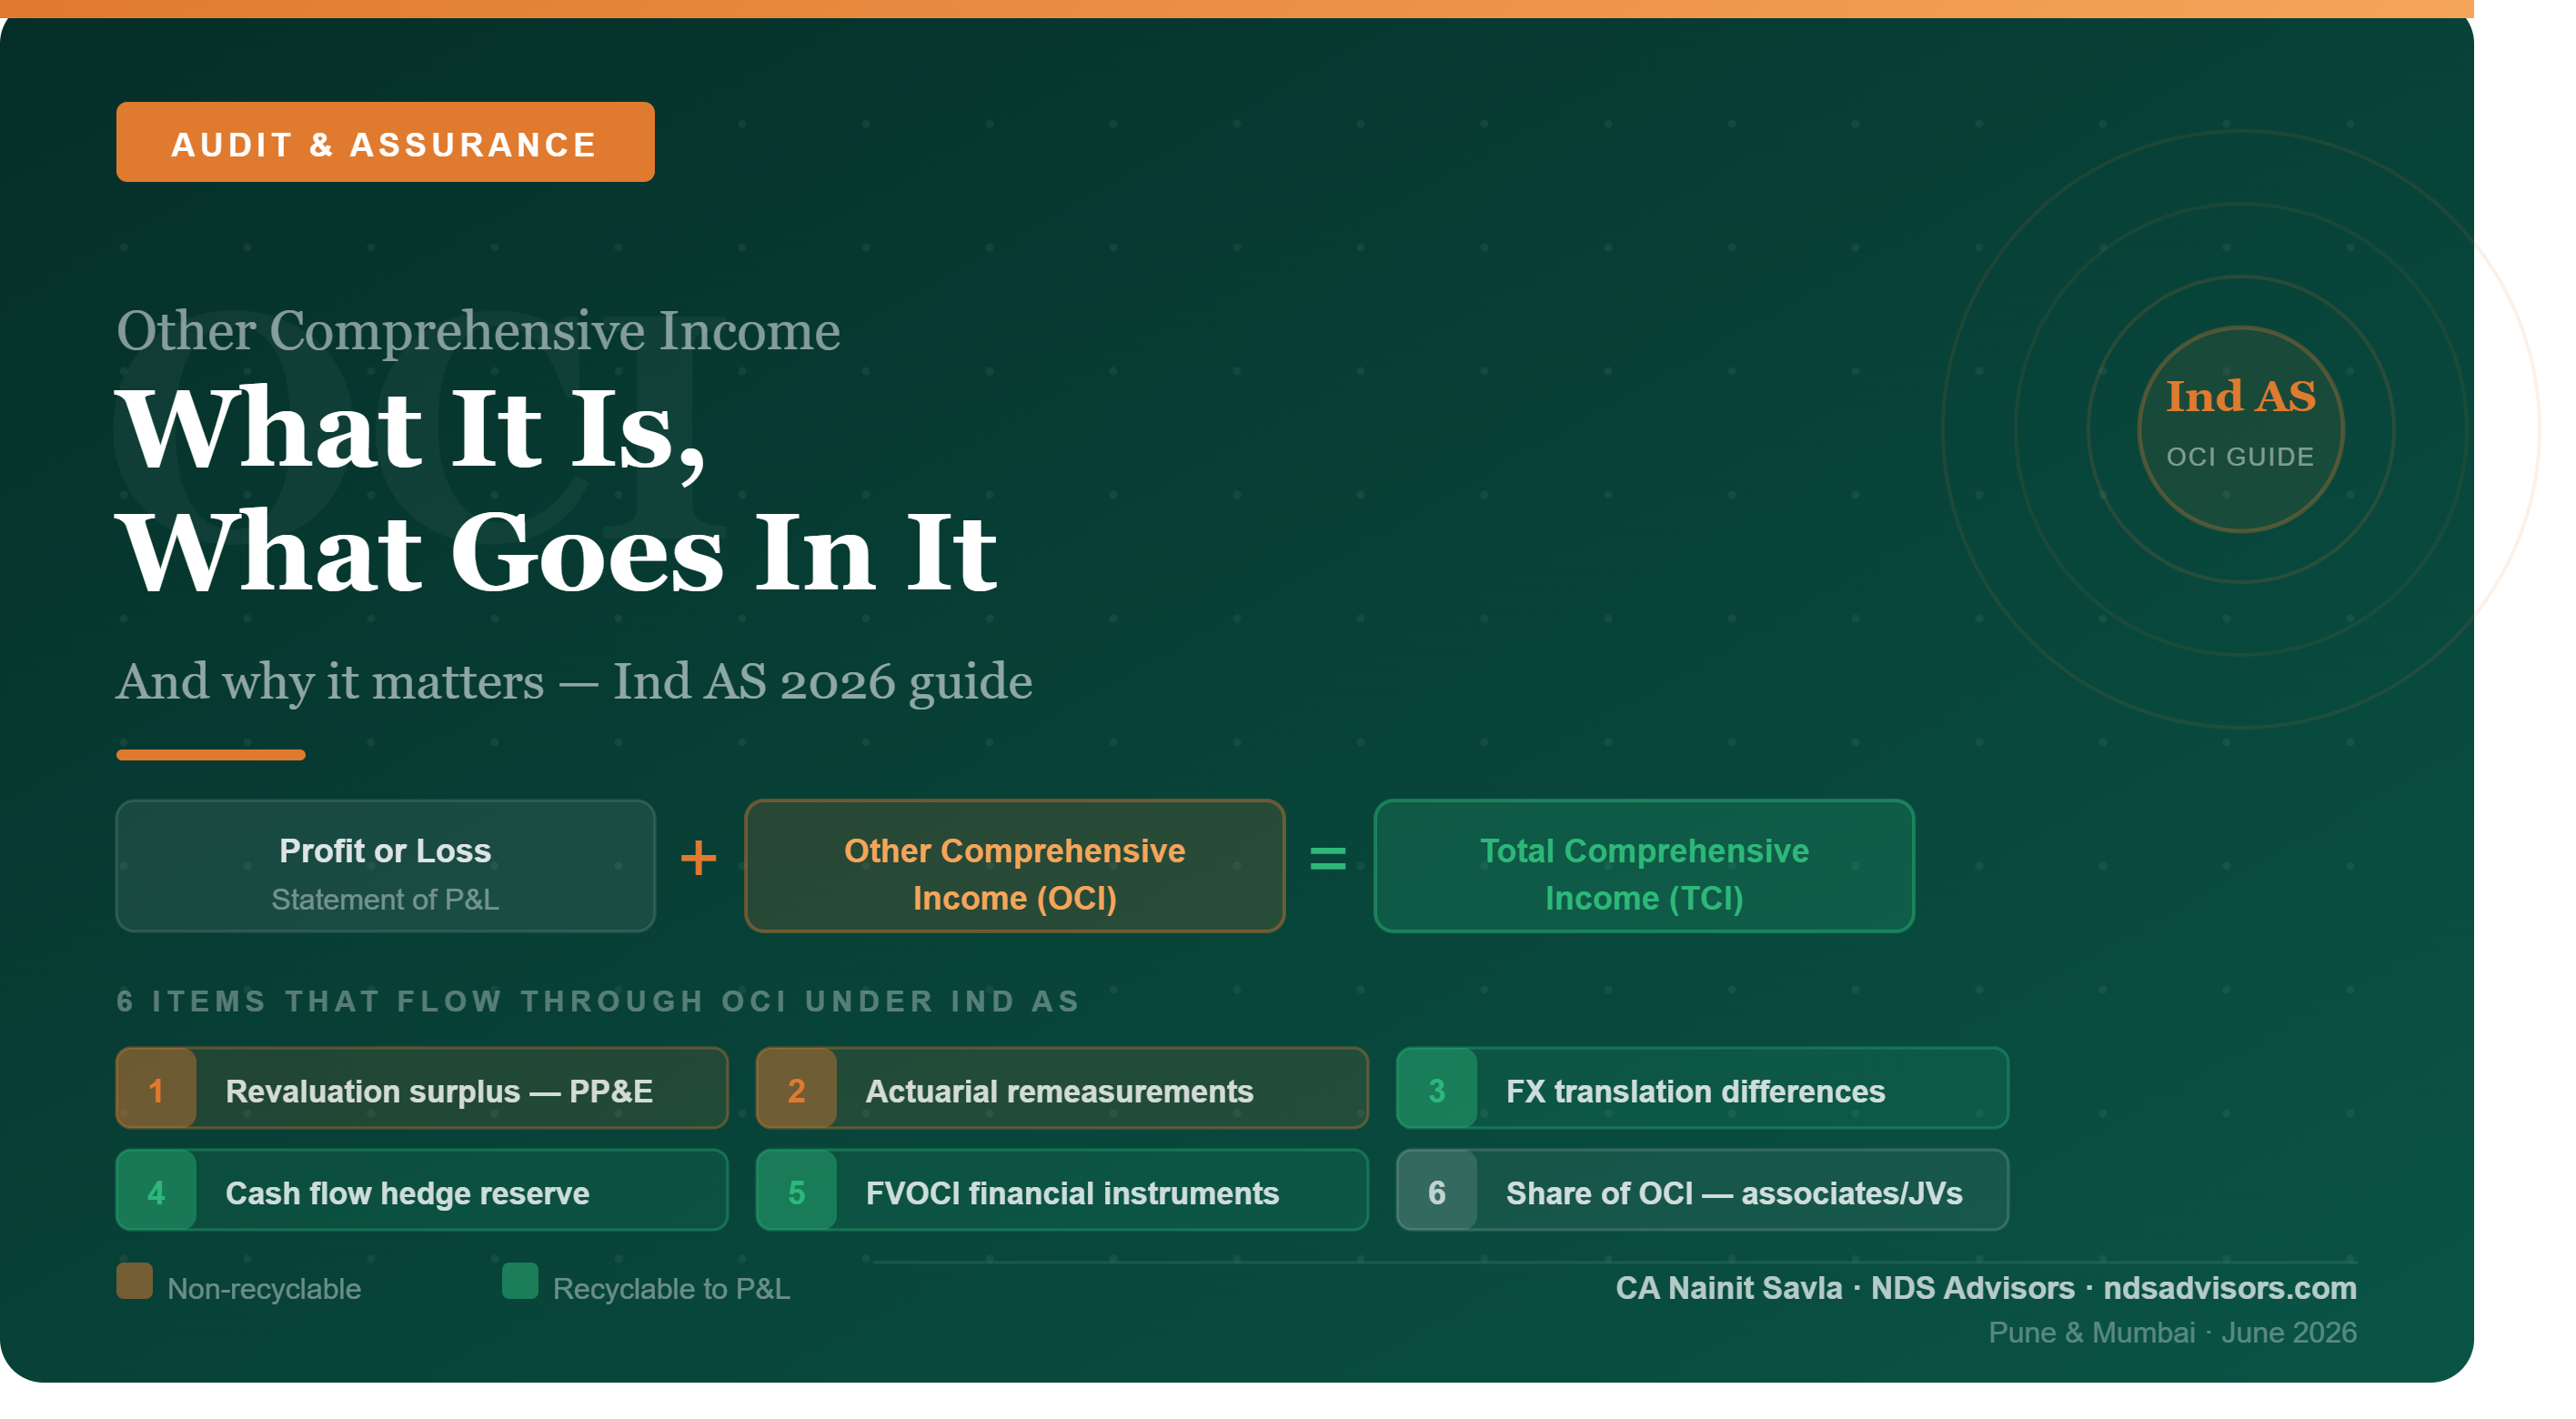
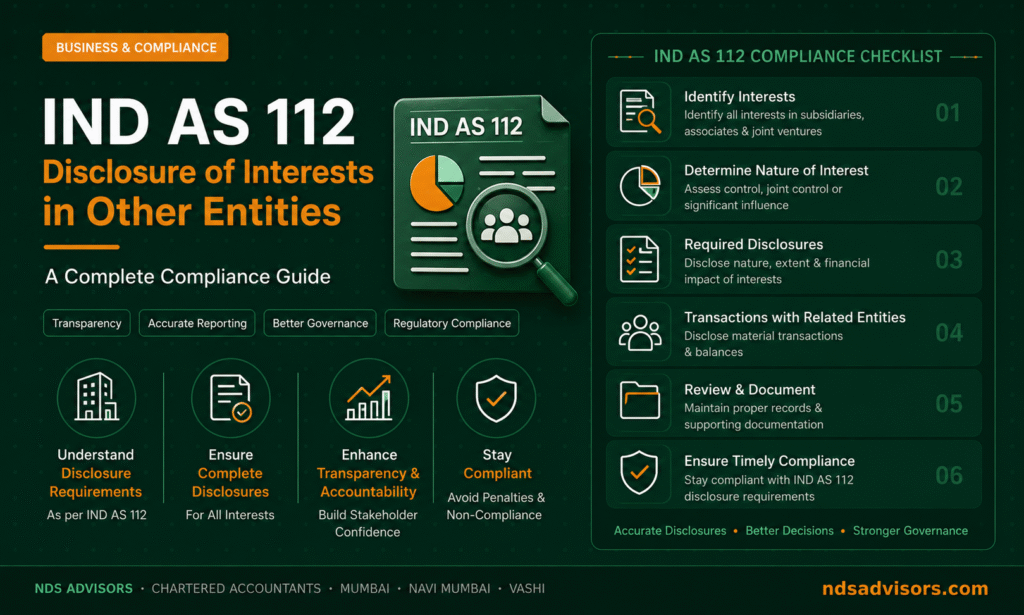
ENTITY INTEREST TYPES — IND AS 112 Reporting Entity Sub- sidiaries Joint Ventures Asso- ciates Structured Entities Full consol. Equity method Equity method Off-balance Ind AS 110 Ind AS 111/28 Ind AS 28 App. A GOVERNED BY: IND AS 112 (= IFRS 12) AUDIT & ASSURANCE Ind AS 112: Disclosure of Interests in Other Entities Subsidiaries · JVs · Associates · Structured Entities SEBI LODR Implications · Judgment Disclosures 5 Entity types 4 Judgment areas 7 Common gaps COVERAGE SCOPE Subsidiaries / NCI JVs & Associates Structured Entities CA Nainit Savla · Founder, NDS Advisors NDS ADVISORS · CHARTERED ACCOUNTANTS Ind AS 112 (Disclosure of Interests in Other Entities) is the standard that tells investors, analysts, lenders, and regulators what a company’s consolidated financial statements do not immediately show: which entities are in the group and why, what restrictions exist on moving assets between group members, how significant the non-controlling interests are in each material subsidiary, what the company’s exposure is to off-balance-sheet structured entities, and what significant judgments management has made in deciding who to consolidate and who to leave out. For listed Indian companies, Ind AS 112 compliance intersects directly with SEBI LODR obligations — the definition of subsidiaries, material subsidiaries, and associates that drives quarterly disclosure obligations, related party transaction reporting, and audit committee review responsibilities flows directly from the Ind AS 110, 111, and 28 framework that Ind AS 112 requires to be disclosed. Getting Ind AS 112 disclosure wrong is therefore not just an accounting standards compliance gap — it can create gaps in regulatory disclosures to stock exchanges. What Is Ind AS 112 and Why Does It Matter? Before the introduction of Ind AS 112 (the Indian equivalent of IFRS 12), disclosure requirements for a company’s interests in other entities were scattered across multiple standards — separate requirements existed for subsidiaries, associates, joint ventures, and off-balance-sheet vehicles, often with inconsistent levels of detail. The result was that a sophisticated investor or lender could read a set of consolidated financial statements without getting a clear picture of the full network of entities the reporting company was involved with, or the risks and restrictions attached to those relationships. The overriding objective of Ind AS 112: to enable users of financial statements to evaluate the nature, extent, and financial effects of the reporting entity’s interests in other entities — and the risks associated with those interests. The standard applies to all entities preparing Ind AS financial statements that have interests in subsidiaries, joint arrangements, associates, or unconsolidated structured entities. For companies that are in the process of or have recently completed Ind AS implementation, the notes required under Ind AS 112 often represent the largest increase in disclosure volume compared to previous Indian GAAP financial statements — particularly for groups with complex ownership structures, offshore entities, or structured financing arrangements. The Five Entity Types Covered Under Ind AS 112 Ind AS 112 covers disclosures for five distinct types of interests. A common mistake is to provide a single combined disclosure for all interests without the entity-type-specific details that the standard requires. Entity Type Relationship Basis Accounting Method Key Ind AS Subsidiaries Control — Ind AS 110 Full consolidation Ind AS 110 Joint Operations Joint control; rights to assets / obligations for liabilities Line-by-line (own share) Ind AS 111 Joint Ventures Joint control; rights to net assets Equity method Ind AS 111 + 28 Associates Significant influence (typically 20–50%) Equity method Ind AS 28 Unconsolidated Structured Entities Interest but not control Off-balance-sheet disclosure Ind AS 112 App. A The Judgment Disclosures — The Most Critical Requirement The most distinctive — and most commonly deficient — aspect of Ind AS 112 is its requirement to disclose significant judgments and assumptions used in determining the nature of interests in other entities. These are not boilerplate disclosures — they must explain the specific reasoning applied in situations where the answer is not obvious from the numbers alone. 1Control Without Majority Voting Rights (De Facto Control) Ind AS 110 defines control on a principles basis: an investor controls an investee when it has power over the investee, exposure to variable returns, and the ability to use its power to affect those returns. This means control can exist with less than 50 percent of the voting rights where, for example, the remaining shares are widely dispersed and in practice the company has always obtained the votes needed to pass resolutions. Where a company consolidates an entity with less than a majority of the voting rights — on the basis of de facto control — Ind AS 112 requires explicit disclosure of the basis for that conclusion: the number of voting rights held, how they compare to the dispersion of remaining rights, and why in practice the company has power over the relevant activities. 2Significant Influence Assessments The 20 percent ownership threshold for significant influence under Ind AS 28 is a rebuttable presumption — it can be overcome in either direction. A company may have significant influence with less than 20 percent if it has board representation, participates in policy decisions, or conducts material intercompany transactions. Equally, a company may hold 25 percent of voting rights but have no practical ability to influence the investee. Ind AS 112 requires disclosure of the basis for the significant influence conclusion in either direction — where influence is asserted below the 20 percent threshold, or where the absence of influence is concluded above it. These disclosures are frequently missing or insufficiently specific in practice. 3Joint Operation vs Joint Venture Classification The classification of a joint arrangement as a joint operation versus a joint venture depends on the rights and obligations of the parties — specifically whether they have direct rights to the assets and direct obligations for the liabilities. The legal form of the arrangement and its contractual terms must both be considered. Where a joint arrangement is conducted through a separate legal entity but is classified as a joint operation based on contractual terms that
Ind AS 112: Disclosure of Interests in Other Entities — A Complete Compliance Guide Read More »