
New Regime vs Old Regime for AY 2026–27: Which Saves You More Tax
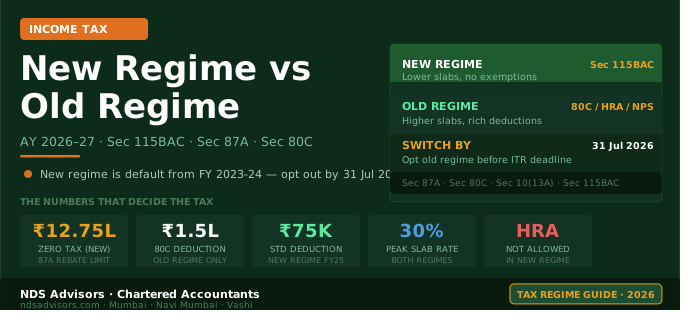
TAX ADVISORY New Regime vs Old Regime for AY 2026-27 Which Saves You More Tax? Slab rates · Worked examples · Break-even deductions NDS Advisors · September 2026 ₹12.75L Effective nil-tax ceiling under the new regime 4 incomes ₹10L, ₹15L, ₹20L, ₹30L worked in full 31 Jul 2026 Filing deadline to lock in your chosen regime NEW REGIME SLABS AT A GLANCE UP TO ₹4,00,000 NIL ₹8,00,001 TO ₹12,00,000 10% SECTION 87A REBATE UP TO ₹12,00,000 ABOVE ₹24,00,000 30% STANDARD DEDUCTION: ₹75,000 NEW · ₹50,000 OLD NDS Advisors · Tax Advisory & Planning TAX ADVISORY · SEPTEMBER 2026 ⚠ There is no universal winner. The new regime wins at low deductions, the old regime catches up and overtakes it as deductions rise, and the break-even point shifts with income. Confirm the current slab rates and thresholds before relying on any figure below. The new tax regime saves more tax for most salaried individuals earning up to ₹12,75,000 per year — they pay zero tax under the new regime thanks to the ₹75,000 standard deduction and the Section 87A rebate for taxable income up to ₹12 lakh. Above that, the two regimes trade the advantage back and forth depending on how much the taxpayer can claim in deductions and exemptions, and the crossover point moves as income rises. The new tax regime saves more tax for most salaried individuals earning up to ₹12,75,000 per year — they pay zero tax under the new regime thanks to the ₹75,000 standard deduction and the Section 87A rebate for taxable income up to ₹12 lakh. For individuals earning ₹15 lakh to ₹30 lakh, the answer depends on one number: total deductions. If your deductions under the old regime — Section 80C, 80D, 80CCD(1B), HRA exemption, home loan interest under Section 24(b), and other eligible deductions — exceed approximately ₹3.75 lakh to ₹4.25 lakh, the old regime typically produces lower tax despite its higher slab rates. Below that deduction threshold, the new regime’s lower rates win. This is the essential framework for the new regime vs old regime comparison for AY 2026–27, and this guide provides the exact slab rates, worked examples at four income levels (₹10 lakh, ₹15 lakh, ₹20 lakh, and ₹30 lakh), and a step-by-step decision process so you can determine which regime saves you more tax. NDS Advisors provides tax advisory services that include personalised old vs new regime analysis for individuals and businesses across India. Key Takeaways The new regime is the default from AY 2024-25. Taxpayers must actively elect the old regime if they want it, rather than the other way around. Zero tax up to roughly ₹12.75 lakh under the new regime. The ₹75,000 standard deduction plus the full Section 87A rebate up to ₹12,00,000 taxable income combine to erase tax entirely for most salaried earners in that band. The break-even deduction level rises with income. Roughly ₹3.75–₹4.25 lakh of deductions at ₹15 lakh income, widening to ₹6.5–₹8 lakh at ₹30 lakh income. The old regime’s advantage is concentrated in a handful of deductions. Home loan interest, HRA, 80C, 80D and 80CCD(1B) are what move the needle; everything else is marginal. The choice can be revisited every year for salaried taxpayers. Those with business or professional income face restrictions on switching back once they opt out of the new regime. What Are the Exact Slab Rates Under the New and Old Tax Regime for AY 2026–27? Table 1 — New Tax Regime Slabs, Section 115BAC (Default from AY 2024-25) Income Slab Rate Up to ₹4,00,000 Nil ₹4,00,001 to ₹8,00,000 5% ₹8,00,001 to ₹12,00,000 10% ₹12,00,001 to ₹16,00,000 15% ₹16,00,001 to ₹20,00,000 20% ₹20,00,001 to ₹24,00,000 25% Above ₹24,00,000 30% Standard deduction ₹75,000 Section 87A rebate Full, up to ₹12,00,000 Most Chapter VI-A deductions (80C, 80D, 80E, 80G, 80TTA) and exemptions (HRA, LTA) are not available under the new regime. Table 2 — Old Tax Regime Slabs Income Slab Rate Up to ₹2,50,000 Nil ₹2,50,001 to ₹5,00,000 5% ₹5,00,001 to ₹10,00,000 20% Above ₹10,00,000 30% Standard deduction ₹50,000 Section 87A rebate Full, up to ₹5,00,000 All deductions remain available under the old regime — 80C (₹1.5L), 80D, 80CCD(1B) (₹50K), HRA, LTA, Section 24(b) home loan interest (₹2L), 80G, 80E, 80TTA. A 4% health and education cess applies to tax under both regimes. How Does the Tax Compare at ₹10 Lakh, ₹15 Lakh, ₹20 Lakh, and ₹30 Lakh Income? The following four worked examples compare the actual tax payable under both regimes for a salaried employee at different income levels, assuming typical deduction scenarios. All examples include 4% cess. Table 3 — Tax Payable at Four Income Levels, New vs Old Regime Gross Salary New Regime Tax Old Regime Tax Winner ₹10,00,000 ₹0 ₹54,600 (₹2.5L deductions) New, by ₹54,600 ₹15,00,000 ₹97,500 ₹1,06,600 (₹5L deductions) New, by ₹9,100 ₹20,00,000 ₹1,92,400 ₹1,95,000 (₹7L deductions) Nearly equal ₹30,00,000 ₹4,75,800 ₹4,75,800 (₹8L deductions) Exactly equal Old regime figures shown are at the deduction level closest to break-even for that income; lower deduction levels favour the new regime by a wider margin. Illustrative figures only — verify against your own numbers. Example 1 — Gross Salary ₹10,00,000: New Regime: Gross salary ₹10,00,000 minus standard deduction ₹75,000 = taxable income ₹9,25,000. Tax: ₹4,00,000 × 0% + ₹4,00,000 × 5% + ₹1,25,000 × 10% = ₹20,000 + ₹12,500 = ₹32,500. But taxable income is below ₹12,00,000, so Section 87A rebate applies — tax = nil. Total tax (new regime) = ₹0. Old Regime (with ₹2.5 lakh deductions — ₹1.5L 80C, ₹25K 80D, ₹50K 80CCD(1B), ₹25K 80TTA): Gross salary ₹10,00,000 minus standard deduction ₹50,000 minus deductions ₹2,50,000 = taxable income ₹7,00,000. Tax: ₹2,50,000 × 0% + ₹2,50,000 × 5% + ₹2,00,000 × 20% = ₹12,500 + ₹40,000 = ₹52,500 + cess ₹2,100 = ₹54,600. Winner: New regime saves ₹54,600. Example 2 — Gross Salary ₹15,00,000: New Regime: ₹15,00,000 minus ₹75,000 = ₹14,25,000. Tax: ₹4L × 0% + ₹4L × 5% + ₹4L × 10% + ₹2,25,000 × 15% = ₹20,000 + ₹40,000 + ₹33,750 = ₹93,750 +
New Regime vs Old Regime for AY 2026–27: Which Saves You More Tax Read More »