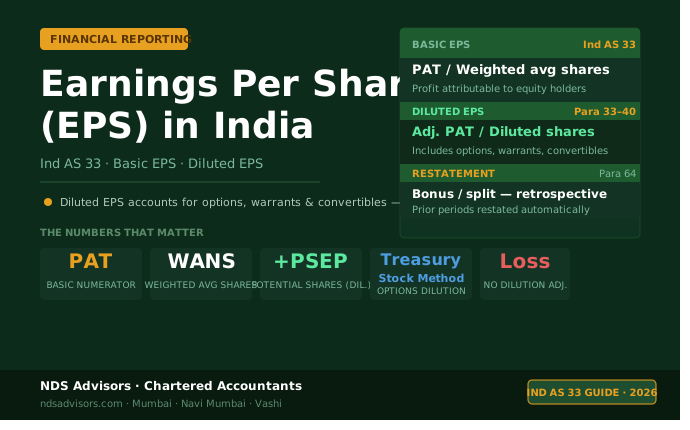
Basic and diluted EPS under Ind AS 33 are calculated by dividing profit attributable to ordinary equity holders of the parent by the weighted average number of equity shares outstanding, with diluted EPS adding back the earnings effect and the share effect of every dilutive potential equity share. The two figures answer different questions. Basic EPS measures what each share earned on the capital actually in issue. Diluted EPS answers a harder question: what would each share have earned if every convertible instrument, option and warrant already outstanding had been exercised?
The formula is short. The judgement sits in the adjustments. Preference dividends that were never declared still reduce the numerator. A bonus issue restates prior years that were already audited. Employee stock options only count when they are in the money. Getting the figure wrong is one of the most common causes of restatement in Indian financial statements, because the number sits on the face of the profit and loss account where every analyst reads it first. Teams that would rather have the calculation reviewed before the auditor does can hand it to our Ind AS implementation team, but every finance controller should still understand the shape of it.
- Two figures, equal prominence. Ind AS 33 requires both basic and diluted EPS on the face of the statement of profit and loss, for continuing operations and for total profit, even when the number is a loss.
- Cumulative preference dividends are deducted whether or not declared. This single distinction between cumulative and non-cumulative shares is where numerator errors concentrate.
- Bonus issues are restated, never time-weighted. Paragraph 64 makes retrospective restatement of every period presented mandatory — even for a bonus issue after the reporting date but before approval.
- Options use the treasury share method. Only the difference between shares issued on exercise and shares notionally repurchased at average market price is added to the denominator.
- Antidilutive instruments are excluded but still disclosed. In a loss-making period every class is antidilutive, so diluted loss per share equals basic loss per share.
What Is Earnings Per Share and Why Does Ind AS 33 Require It?
Earnings per share is the portion of an entity’s profit attributable to each equity share outstanding during a reporting period. Ind AS 33, Earnings per Share, prescribes how it is measured and presented so the figure means the same thing across companies and periods. The Ind AS 33 earnings per share requirement is about comparability before computation: without a common denominator rule, two identical businesses could report materially different EPS simply by counting shares differently.
Anyone asking what earnings per share means in a reporting context is really asking about comparability. Ind AS 33 standardises the denominator rather than defining profit. It takes profit as the other standards measure it and concentrates on which shares count, for how much of the year, and which potential shares must be assumed into existence. That is why the EPS calculation under Ind AS 33 becomes mechanical once share movements are mapped correctly.
Which Companies Must Report Basic and Diluted EPS Under Ind AS 33?
Ind AS 33 applicability starts with a scope test: the standard applies to entities whose ordinary shares or potential ordinary shares are publicly traded, and to entities in the process of issuing shares in a public market. Where an entity presents both consolidated and separate financial statements, the EPS information required by the standard is presented in the consolidated statements.
In practice Ind AS 33 applicability is wider than that scope test suggests. Division II of Schedule III to the Companies Act, 2013 requires earnings per equity share, basic and diluted, on the face of the statement of profit and loss for every company preparing Ind AS financial statements. So an unlisted company inside the roadmap presents EPS even though the standard’s own scope paragraph would not compel it.
The roadmap is set by the Companies (Indian Accounting Standards) Rules, 2015. Phase I covered listed and unlisted companies with net worth of ₹500 crore or more from FY 2016-17. Phase II added all remaining listed companies other than those on SME exchanges, and unlisted companies with net worth of ₹250 crore or more, from FY 2017-18, together with their holding, subsidiary, joint venture and associate entities. Companies outside the roadmap apply AS 20 under the Companies (Accounting Standards) Rules, 2021. Plan a conversion to Ind AS before the year you are caught, not during it.
How Do You Calculate Basic EPS Under Ind AS 33?
The basic EPS formula divides profit or loss attributable to ordinary equity holders of the parent entity by the weighted average number of shares outstanding during the period. Both halves of that basic EPS formula need work before the division makes sense, and this is where the EPS calculation under Ind AS 33 stops being arithmetic.
On the numerator, start with profit or loss from continuing operations attributable to the parent, then deduct the after-tax amount of preference dividends. The distinction that catches teams out is between cumulative and non-cumulative preference shares. For cumulative preference shares the dividend for the period is deducted whether or not it has been declared. For non-cumulative shares it is deducted only if declared. Any excess paid on settlement or repurchase of preference shares is also deducted.
Ind AS 33 carries an India-specific rule with no equivalent in IAS 33. Where an item of income or expense that would otherwise go through profit or loss is instead debited or credited to securities premium or another reserve because a law requires it, that amount is adjusted against profit from continuing operations for basic EPS. Auditors reviewing the audit and assurance file test for it specifically, because it is easy to miss when the entry never touched the profit and loss account.
How Is the Weighted Average Number of Shares Calculated?
The weighted average number of shares is the number outstanding at the start of the period, adjusted for shares issued or bought back during the period weighted by the portion of the period they were outstanding. Shares issued for cash are included from the date the consideration is receivable. Shares issued on conversion of a debt instrument are included from the date interest stops accruing. Treasury shares are excluded throughout.
Bonus issues and share splits break that pattern, and this is where errors concentrate. A bonus issue brings in no new resources, so there is nothing to time-weight. Instead the bonus issue EPS adjustment restates the share count for every period presented as if the extra shares had always existed. The same retrospective treatment applies to share splits and, in reverse, to share consolidations.
A rights issue priced below fair value is a hybrid. Part of it is a genuine issue of shares for cash and part is a bonus element given free to existing holders. Ind AS 33 separates the two using an adjustment factor: fair value per share immediately before the exercise of rights, divided by the theoretical ex-rights fair value per share. Shares before the rights issue are multiplied by that factor, and the bonus issue EPS adjustment logic then applies to the bonus portion across comparatives.
How Do You Calculate Diluted EPS Under Ind AS 33?
Diluted EPS assumes every dilutive potential equity share has already been converted, and adjusts both the numerator and the denominator to match. These six steps set out how to calculate diluted EPS in the order the standard applies them.
- Start from the basic EPS numerator. Take profit or loss attributable to ordinary equity holders of the parent, after the preference dividend and reserve adjustments already made for basic EPS. This is the control number against which every instrument is tested for dilution.
- List every potential equity share in issue. Convertible debentures, convertible preference shares, employee stock options, warrants and contingently issuable shares all qualify. The test is whether the instrument could entitle its holder to equity shares, not whether anyone expects conversion.
- Test each instrument separately for dilution. An instrument is dilutive if converting it reduces earnings per share from continuing operations or increases loss per share. Antidilutive potential equity shares are excluded from the calculation entirely, even though they must still be disclosed.
- Apply the treasury share method to options and warrants. Assume the options are exercised, then assume the proceeds are used to buy shares at the average market price for the period. Only the difference between the shares issued on exercise and the shares notionally repurchased is added to the denominator. Options are dilutive only when the exercise price is below the average market price for the period.
- Adjust the numerator for convertible instruments. Add back interest on dilutive convertible debt net of tax, add back dividends on dilutive convertible preference shares, and adjust for any other change in income or expense that conversion would cause. Options and warrants change only the denominator, since no interest or dividend disappears on exercise.
- Rank the instruments and compute in sequence. Where several classes exist, rank them from most to least dilutive by incremental earnings per incremental share, then bring them in one class at a time. Sequencing matters because an instrument that is dilutive alone can turn antidilutive once a more dilutive class is already in the denominator.
Basic and Diluted EPS: A Worked Example Under Ind AS 33
Assume Vertex Components Limited reports profit after tax attributable to owners of the parent of ₹8,40,00,000 for FY 2025-26. It has ₹1,00,00,000 of 10% cumulative preference shares on which no dividend was declared, 40,00,000 equity shares outstanding on 1 April 2025 and a further 12,00,000 shares issued for cash on 1 October 2025. It also has 4,00,000 employee options exercisable at ₹120 against an average market price of ₹200, and ₹2,00,00,000 of 9% debentures convertible into 5,00,000 equity shares, outstanding all year, with tax at 25%.
| Particulars | Amount |
|---|---|
| Profit attributable to owners of the parent | ₹8,40,00,000 |
| Less: cumulative preference dividend (not declared, still deducted) | (₹10,00,000) |
| Basic EPS numerator | ₹8,30,00,000 |
| 40,00,000 shares × 12/12 | 40,00,000 |
| 12,00,000 shares × 6/12 | 6,00,000 |
| Weighted average number of shares | 46,00,000 |
| Basic EPS | ₹18.04 |
| Add: options — 4,00,000 less (₹4,80,00,000 ÷ ₹200) | 1,60,000 |
| Add: shares on conversion of debentures | 5,00,000 |
| Diluted denominator | 52,60,000 |
| Add: debenture interest ₹18,00,000 net of 25% tax | ₹13,50,000 |
| Diluted numerator | ₹8,43,50,000 |
| Diluted EPS | ₹16.04 |
Illustrative figures only. Verify each adjustment against your own share register and the current text of Ind AS 33 before relying on the method.
Both instruments are dilutive. The options carry no incremental earnings against 1,60,000 incremental shares, so they rank first. The debentures add ₹13,50,000 against 5,00,000 shares, or ₹2.70 per incremental share, well below basic EPS of ₹18.04 and therefore still dilutive. Reported basic and diluted EPS are ₹18.04 and ₹16.04 respectively.
Which Potential Equity Shares Are Dilutive and Which Are Antidilutive?
Dilutive potential equity shares reduce EPS from continuing operations on conversion. Antidilutive potential equity shares increase it, or reduce a loss per share, and Ind AS 33 requires them to be left out. The comparison is always against profit or loss from continuing operations attributable to the parent, not against total profit, so a company with a large discontinued operation can reach a different answer than a quick look at the bottom line would suggest.
Out-of-the-money options are the clearest example
Where the exercise price sits above the average market price, exercising brings in more cash than the shares are worth, EPS rises, and the options are excluded. The same instruments can flip between dilutive and antidilutive as the average market price moves, so the test is performed every reporting period rather than carried forward.
A loss-making period makes every class antidilutive
Adding shares to the denominator would reduce the loss per share, so diluted loss per share equals basic loss per share. That is a presentation outcome, not an exemption. Both figures are still reported and the excluded instruments still disclosed.
What Are the EPS Disclosure Requirements Under Ind AS 33?
The Ind AS 33 earnings per share disclosure requirements start on the face of the statement of profit and loss. Basic and diluted amounts are presented with equal prominence for each class of ordinary share carrying a different right to share in profit, for profit or loss from continuing operations and for profit or loss for the period, and for every period presented.
Where a discontinued operation is reported, its EPS is disclosed on the face or in the notes. The notes also carry the numerators reconciled to profit attributable to the parent, the weighted average number of shares used as each denominator with a reconciliation between them, instruments that were antidilutive this period but could dilute later, and share transactions after the reporting date that would have changed the count significantly.
Listed entities carry a second layer of EPS disclosure requirements. Regulation 33 of the SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015 requires EPS in quarterly results, where the weighted average has to be recomputed each quarter and for the year to date rather than annualised from an earlier figure. Companies that treat quarterly EPS as a spreadsheet carry-forward tend to discover the error at the year-end statutory audit under the Companies Act, 2013.
| Disclosure | Where It Sits | Governing Source |
|---|---|---|
| Basic and diluted EPS, equal prominence | Face of the statement of profit and loss | Ind AS 33; Schedule III, Companies Act, 2013 |
| EPS for continuing operations and total profit | Face of the statement of profit and loss | Ind AS 33 |
| EPS of a discontinued operation | Face or notes | Ind AS 33 |
| Numerator reconciliation to profit attributable to parent | Notes | Ind AS 33 |
| Weighted average denominators with reconciliation | Notes | Ind AS 33 |
| Antidilutive instruments that may dilute later | Notes | Ind AS 33 |
| Material share transactions after the reporting date | Notes | Ind AS 33 |
| Quarterly and year-to-date EPS for listed entities | Quarterly financial results | Regulation 33, SEBI LODR, 2015 |
How Has EPS Reporting in India Changed Since 1991?
EPS reporting in India moved from a voluntary footnote to a regulated line item over roughly three decades. Before 1991 there was no accounting standard on the subject. Schedule VI to the Companies Act, 1956 did not require earnings per share and disclosure was inconsistent where it appeared at all. It also mattered less, because the Controller of Capital Issues fixed issue prices administratively, and when the regulator sets the price a per-share figure carries little signalling value.
Liberalisation changed the economics. The Controller of Capital Issues was abolished in 1992 and SEBI took over, free pricing of public issues arrived, and per-share earnings became central to how issues were valued. The ICAI responded with AS 20, Earnings Per Share, mandatory for listed companies from 1 April 2001, which introduced weighted averaging and diluted EPS into Indian practice for the first time.
Today the framework runs through Section 133 of the Companies Act, 2013 and the Companies (Indian Accounting Standards) Rules, 2015, notified by the Ministry of Corporate Affairs and available on the MCA portal. Ind AS 33 converged Indian practice with IAS 33 from FY 2016-17. One further change is scheduled: the National Financial Reporting Authority recommended Ind AS 118, Presentation and Disclosure in Financial Statements, for notification in December 2025, proposed to apply from 1 April 2027, with consequential amendments to Ind AS 33 that restrict which numerators a company may use for additional per-share measures. Teams planning an Ind AS implementation should build for that timetable.
What Do Finance Teams Get Wrong About Basic and Diluted EPS?
Four errors account for most of the corrections auditors raise on basic and diluted EPS.
- Undeclared cumulative preference dividends left in the numerator. For cumulative shares the dividend is deducted whether or not it has been declared — leaving it in overstates basic EPS.
- Bonus issues time-weighted instead of applied retrospectively. A bonus issue brings in no new resources, so it restates every period presented rather than being weighted by date.
- Options added to the denominator in full. Only the treasury share method increment belongs in the denominator, not the whole option count.
- Antidilutive instruments included. Someone assumed dilution always reduces EPS; where conversion would raise EPS the instrument is excluded and merely disclosed.
A fifth is structural rather than arithmetical, and it undoes an otherwise correct EPS calculation under Ind AS 33: the figure is computed once at year-end from a share register nobody reconciled during the year. Tracking allotments, buybacks and option grants as they happen through financial reporting and MIS turns the year-end calculation into a check rather than a reconstruction.
Why Finance Teams Work with NDS Advisors on EPS
- The calculation is reviewed before the auditor sees it: we test the numerator adjustments, the weighted average and the dilution ranking, not after a query is raised.
- Share movements tracked through the year: allotments, buybacks and option grants captured as they happen, so year-end is a check rather than a reconstruction.
- Bonus and rights issues handled correctly: retrospective restatement under Paragraph 64 and the rights-issue adjustment factor applied across all comparatives.
- Full disclosure package prepared: face-of-statement figures, note reconciliations and the antidilutive instruments carried forward.
- Built for the road ahead: computations set up with the proposed Ind AS 118 amendments and the FY 2027 timetable in mind.
Frequently Asked Questions
What is earnings per share under Ind AS 33?
What is the difference between basic and diluted EPS?
Which companies must present basic and diluted EPS in India?
Are antidilutive potential equity shares included in diluted EPS?
Can basic EPS and diluted EPS be the same figure?
How is the weighted average number of shares treated for a bonus issue?
The bottom line
The Ind AS 33 EPS formula is short, but the number is only as good as the adjustments behind it. Deduct cumulative preference dividends whether or not declared, restate bonus issues retrospectively, run options through the treasury share method, and leave antidilutive instruments out while still disclosing them. Track share movements through the year so the year-end figure is a check rather than a reconstruction — that is what keeps EPS off the restatement list.
Suite No. 102, L1, Ashok Premises, Nicholas Road, Andheri (East), Mumbai 400069 · Mon–Sat, 10:00 AM – 7:00 PM
Written by the team at NDS Advisors, Chartered Accountants
Andheri (East), Mumbai · Navi Mumbai · Vashi · pan-India
An ICAI-registered firm with over fifteen years in practice, advising on audit and assurance, direct and indirect tax, Ind AS and IFRS implementation, corporate advisory and accounting outsourcing. Every article published on ndsadvisors.com is reviewed against the current provisions of Indian corporate and accounting standards before publication.